All Categories
Featured


Professional Tips for Small Business Benefit Strategy
Table of Contents
Keep your group pleased, healthy, and engaged. We'll direct you to the best medical insurance strategy while navigating compliance and remaining within your budget plan. Enroll your staff members seamlesslyChoose from multiple top-tier strategy providersIntegrate easily with your payroll.
Do you know how to select medical insurance prepares for your organization? Sure, you could use standard group medical insurance to your workers, however that's not your only choice. There are a number of small company health insurance options you can select from. Why not pick the program that fits your business? Read on to discover little organization healthcare options to help you pick one that keeps your workers (and spending plan) delighted.
QSEHRA: small employers under 50 repay employees for private premiums and medical costs; tax-deductible for employers. ICHRA: any employer can reimburse workers for individual plan expenses, must correspond within worker classes and is tax-free. Excepted benefit HRA: supplemental compensations for dental, vision, copays; should accompany a standard group strategy.
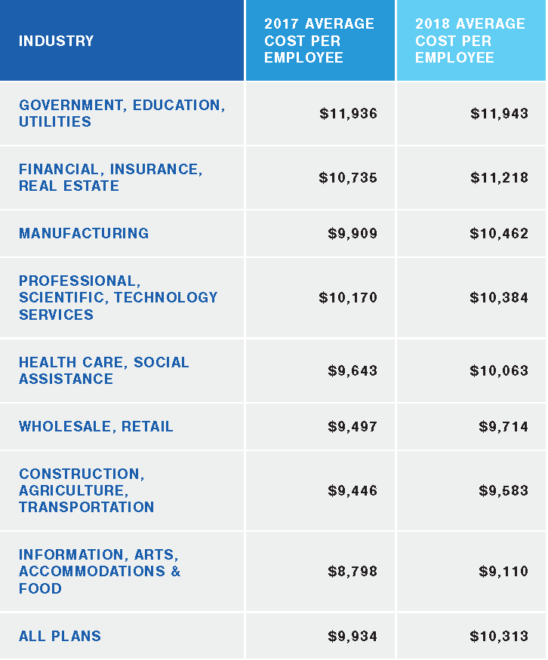
Companies pay around for single coverage and each year for a worker with family coverage insurance coverage. Luckily, small organization owners have some program alternatives and tax rewards that aren't offered to bigger companies (e.g., employers with 50 or more employees). Take a look at some of the health insurance coverage options for little company owners below.
Conventional group medical insurance is where an employer chooses a plan, or strategies, to use staff members. Normally, the company foots part of the bill, and the staff member pays the other part. how much does health insurance coverage cost? With a standard group health insurance coverage strategy, employers and staff members pay regular monthly premiums.
The worker is also accountable for copays and deductibles related to the strategy they pick. Take an appearance at some truths about traditional group medical insurance strategies: Companies choose plans to use staff members Workers contribute pre-tax premiums toward their plan Companies typically contribute an excellent part of the premium expense Streamline Health Benefits Administration Our totally free integration with SimplyInsured lets you buy medical insurance plans, compare expenses, just management, and automatically sync advantages deductions with Patriot's payroll software application.
Navigating 2026 Employee Group Benefits
What is it? QSEHRAs are standard group health strategy options that let companies compensate employees for individually-obtained premiums and eligible medical expenditures. Typically, HRAs compensate workers for certain medical costs, such as medication or crutches. However, a QSEHRA is a standalone HRA that compensates staff members for premiums, too. Here are a couple of quick realities about Certified Small Employer Health Reimbursement Arrangements: Just small companies with less than 50 full-time equivalent (FTE) employees can use a QSEHRA Employers can not offer another kind of health insurance coverage if providing a QSEHRA Company owner can deduct QSEHRA contributions from taxes Companies need to offer QSEHRAs to all eligible staff members The 2026 QSEHRA contribution limitation is $6,450 for single protection and $13,100 for family coverage ICHRA represent Private Coverage Health Repayment Plan.
Business Insurance Long BeachUnlike traditional health insurance coverage plans, employers with an ICHRA do not straight provide plans to staff members. Rather, staff members pick their own health insurance coverage plan, and companies compensate them for the cost of part or all of their strategy. Individual Protection Health Reimbursement Arrangements aren't specific to little companies. Any employer can use them, but employers with 50 or more staff members (i.e., applicable large companies) need to ensure the strategy is affordable, which the IRS defines.
Employers can not provide both to a staff member ICHRAs are tax-free Employers with 50 or more staff members have stricter regulations for ICHRA compensations An excepted benefit HRA is an extra insurance coverage option that started in January 2020. Companies can just provide an excepted advantage HRA if they also offer a conventional health insurance plan.
Affordable Group Health Coverage Plans Today
How do these plans work? Through an excepted advantage HRA, companies compensate staff members for eligible expenditures. Inspect out some of these truths about excepted benefit HRAs: The yearly contribution limitation is $2,200 for 2026 It should be used in combination with a conventional group medical insurance strategy Excepted benefit HRAs do not pay for main health insurance coverage premiums There are a number of differences in between the small service medical insurance options out there.

Table of Contents
Latest Posts
Top Employee Health Trends Local Companies Should Watch
How Strategic Dental Benefits Support Talent
Comprehensive Benefits: Including Healthcare Facility Indemnity to Group Plans
Latest Posts
Top Employee Health Trends Local Companies Should Watch
How Strategic Dental Benefits Support Talent
Comprehensive Benefits: Including Healthcare Facility Indemnity to Group Plans